
Does Checking Your Credit Score Affect It?

Quick answer: No — checking your own credit score never lowers it. When you look at your own report, the agency records a soft search, and soft searches don't touch your score, no matter how often you check. What can ding you is a hard search, which happens when a lender checks your file because you applied for credit. One hard search barely matters. A bunch of them in a short space of time does. So check away — and save your worry for the applications.
Here's the fear that keeps people away from their own credit file: if I look at my score, will looking make it worse? It's a fair question, because credit scores feel fragile, and nobody wants to break something by poking at it. The good news is simple. Your own checks are invisible to lenders. They sit on your file as soft searches, and lenders don't use them when they decide anything about you. The confusion comes from mixing up two very different kinds of check — and once you can tell them apart, the whole thing stops being scary.
There's a real cost to not checking, by the way. The FCA's Financial Lives survey found that 34% of UK adults got their credit report or checked their score in the 12 months to May 2024, up from 28% in 2022 — and 10% of those who checked found an error or issue, which the FCA puts at around 1.8 million adults. Errors you never see are errors you never fix. A wrong default or an account you don't recognise can do far more damage than any number of your own checks ever will.
Soft vs hard searches at a glance
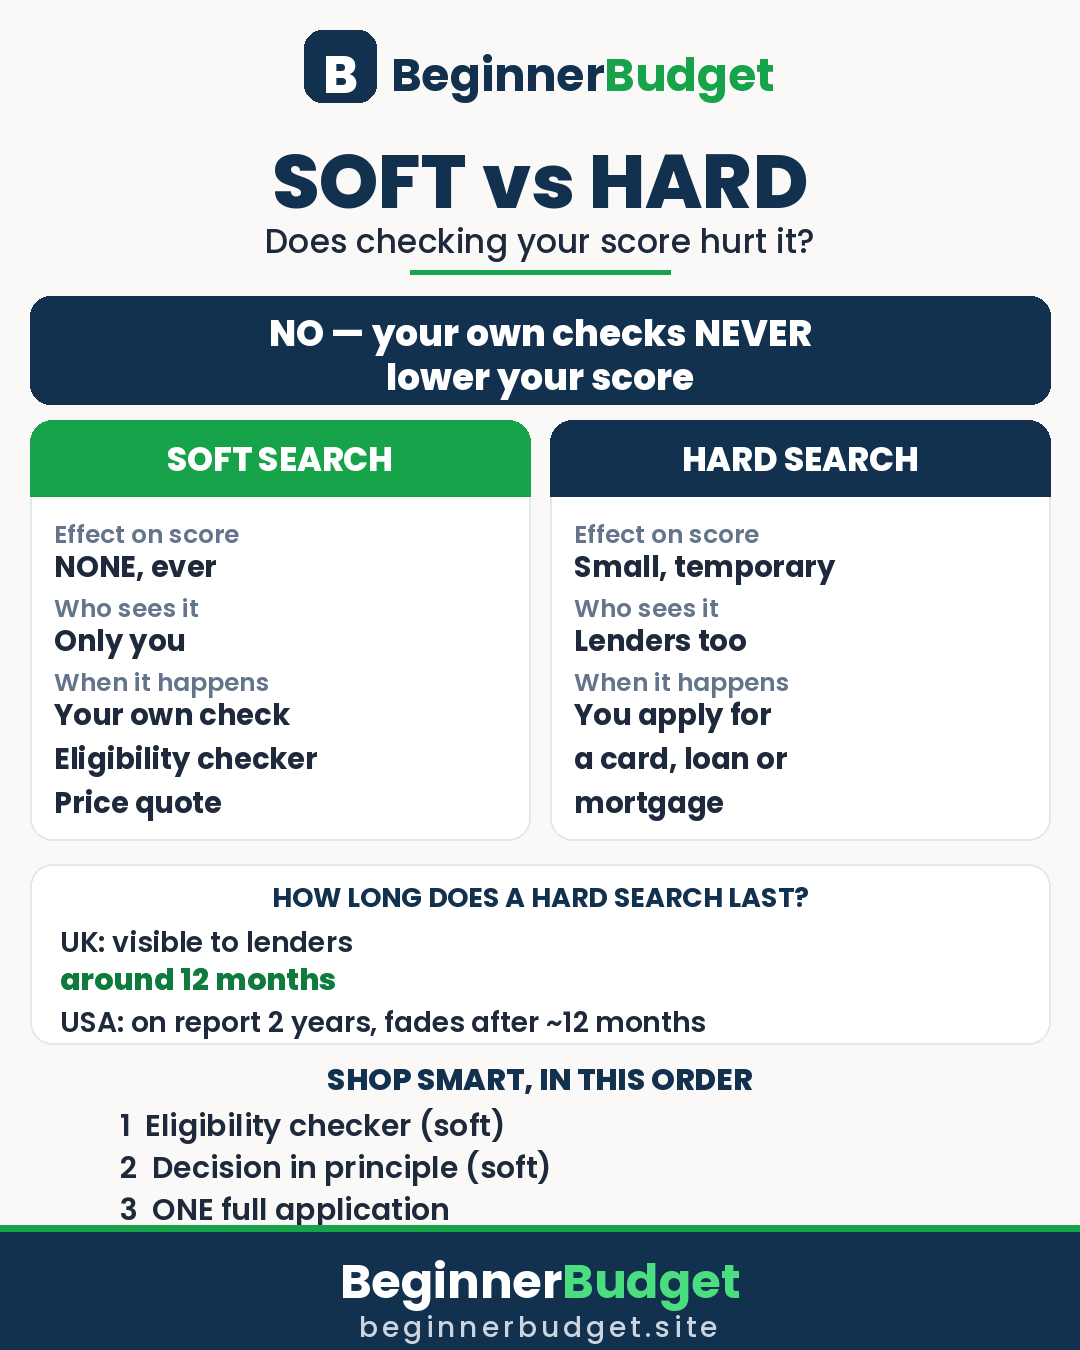
Every time someone looks at your credit file, it leaves a record called a search (in the USA, it's called an inquiry). There are two kinds, and they could hardly be more different. One is harmless background noise. The other is a signal that you just asked someone for money.
| Soft search | Hard search | |
|---|---|---|
| When it happens | You check your own file, run an eligibility check, or get a quote | You formally apply for credit — a card, loan, mortgage, or finance deal |
| Who can see it | Only you | You and any lender who checks your file later |
| Effect on your score | None, ever, however many there are | Small and temporary — one search rarely matters on its own |
| How long it shows (UK) | Visible to you only; lenders never see it | Visible to lenders for around 12 months |
| How long it shows (USA) | Not shown to lenders at all | Stays on your report for 2 years; score impact fades after about 12 months |
| Examples | Checking ClearScore or Experian, a price comparison, an eligibility checker | A mortgage application, a credit card application, car finance |
What is a soft search?
A soft search is a peek at your file that isn't a credit application. Nobody is deciding whether to lend you money, so nothing about it can count against you. The agency still records it — you'll see it listed on your own report — but lenders never see that list, and it plays no part in any score.
Soft searches happen far more often than most people realise, and every one of these is safe:
- Checking your own score or report — through Experian, Equifax, TransUnion, ClearScore, Credit Karma, or your bank's app. Daily, weekly, hourly — it makes no difference.
- Eligibility checkers — the "will I get this card?" tools on comparison sites. They exist precisely so you can shop around without leaving marks.
- Price comparison quotes — insurance and loan quotes usually start with a soft search.
- Identity checks — when a company verifies who you are, for example when you open an account or pass a security check.
- Pre-approvals and "you're eligible" offers — a lender soft-checking its own existing customers before sending an offer.
One thing worth knowing: you can't "fail" a soft search. There's no application attached to it, so there's no decision to go against you. If a comparison site says a card isn't a great match, that's its own eligibility guess — not a mark on your file.
What is a hard search?
A hard search is the full check a lender runs when you actually apply for credit. You're asking for money, so the lender wants the complete picture: your accounts, your payment history, your existing borrowing, and how many other people you've asked recently. That check gets recorded, and other lenders can see it afterwards.
The logic is straightforward. If someone applies for five credit cards in a fortnight, lenders want to know — it can look like someone scrambling for credit. One application, on the other hand, looks like normal life. People apply for things. Lenders know that.
Hard searches also show up in places people don't expect. Some mobile phone contracts, car finance deals, and rental applications involve one. The rule of thumb: if you're signing up for something where a company takes a financial risk on you — lending you money, or letting you pay monthly for something expensive — assume a hard search is possible, and ask before you apply if it matters to you.
How much does a hard search actually hurt?
Less than you'd think, and less than most articles imply. There's no fixed number of points a hard search costs you — it depends on your file. Someone with a long, clean history will barely notice one. Someone with a thin file (not much credit history yet) will feel it more, because there's less good history to balance it out.
What actually does the damage is the pattern, not the single event. ClearScore puts it plainly: a single hard search has only a small, short-term impact, but several applications close together can make you look as if you're taking on credit quickly, which can lower your score for a short time. Experian says the same — checking your own report or score won't affect your score or your chances of being accepted, however many times you check. The damage, when it comes, comes from the applications, not the looking.
And here's the part people forget: the effect fades. In the UK, a hard search stops being visible to lenders after around 12 months. In the USA, it stays on your report for 2 years, but its effect on your FICO score fades after about 12 months. Either way, a hard search is a temporary bruise, not a permanent scar — unlike a missed payment or a default, which hang around for six years in the UK.
Checks you can run without any worry
If you take one habit from this article, make it this: use soft searches aggressively before you ever let anyone run a hard one. That's what they're for. Before applying for a credit card, run the eligibility checker first — it tells you your realistic chances without touching your score. Before a mortgage, get a decision in principle from lenders that use a soft search for it (most do, but ask — a few still use a hard one at that stage). Before a loan, compare quotes on a comparison site rather than applying to three lenders directly.
The same goes for your own file. Our guide to checking your credit score free in the UK walks through the free routes at each agency, and the free statutory report each agency must provide on request. There's no reason to pay a monthly subscription just to look at your own file, and no reason to ration your checks. The FCA found 81% of UK adults knew they could check their report or score in 2024 — if you're in the other 19%, now you know too.
Applications that do leave a hard search
So what actually triggers one? The honest answer is "any formal credit application", but here are the ones that catch people out:
- Credit card applications — every one, approved or declined. A declined application still leaves the search behind.
- Loans and mortgages — full applications, not decisions in principle (those are usually soft).
- Car finance and store finance — that "0% for 12 months" deal at the till is still a credit application.
- Some mobile and broadband contracts — monthly contracts where the provider extends you credit for the handset or service.
- Some buy-now-pay-later plans — rules vary by provider and plan size, and reporting in this area is expanding. If you're using BNPL for a big purchase, check whether the provider runs a hard search first.
- Some rental and business checks — a small number of referencing checks are hard rather than soft. Ask the agent which kind they run.
None of this means you should avoid applying for credit. Credit exists to be used. It means: apply when you've got a real reason, space applications out, and don't fire off five applications in a week hoping one sticks. That's the pattern lenders notice.
How long does a hard search stay on your file?
It depends where you live, and it's worth knowing both versions because the numbers get mixed up online all the time:
| UK | USA | |
|---|---|---|
| Visible to other lenders | Around 12 months | 2 years on your report |
| Effect on your score | Fades well before it disappears from view | Mostly felt in the first 12 months, then fades |
| Your own soft searches | Visible only to you, forever harmless | Not visible to lenders at all |
| Missed payments / defaults (for comparison) | 6 years | Up to 7 years |
Put that in perspective: a single hard search is a 12-month footnote. A missed payment is a six-year headline. If you're choosing what to worry about, worry about the payments, not the searches.
Rate shopping: how to compare loans without the damage
Here's where people get tripped up. You want the best mortgage rate, so you apply to four lenders. Each one runs a hard search. Now your file shows four applications in a month, and lender number five is wondering why everyone's saying no. Don't do it that way.
Do it this way instead. First, use eligibility checkers and comparison sites — all soft, all free. Second, get decisions in principle from lenders that confirm they use a soft search at that stage. Third, use a broker if you're going for a mortgage: a good broker checks each lender's criteria against your situation before anyone applies anywhere, so the one full application you make is the one most likely to succeed. In the USA, there's an extra protection built into the scoring models: FICO treats multiple mortgage, auto or student loan inquiries made within a short window — typically 14 to 45 days depending on the model — as a single inquiry, precisely because rate shopping is normal behaviour. The UK has no formal window like that, which is exactly why the soft-first approach matters more here.
UK vs USA: what changes across the Atlantic
The words change, the principle doesn't. In the UK, agencies are Experian, Equifax and TransUnion, and each gives you its own score on its own scale — Experian runs 0–999, Equifax 0–1000, TransUnion 0–710. There's no single "UK credit score", so compare the same agency month to month and ignore the gaps between them. In the USA, the bureaus are the same three names (Experian, Equifax, TransUnion), but the score most lenders use is FICO, on a 300–850 scale, and the language is "hard inquiry" instead of "hard search".
| UK | USA | |
|---|---|---|
| Agencies / bureaus | Experian, Equifax, TransUnion | Experian, Equifax, TransUnion |
| Main score | Each agency's own (e.g. Experian 0–999) | FICO 300–850 |
| Your own check | Soft search — no effect, ever | Soft inquiry — no effect, ever |
| Application check | Hard search — visible ~12 months | Hard inquiry — on report 2 years |
| Rate-shopping protection | None formal — use soft checks first | FICO counts same-type inquiries in a 14–45 day window as one |
| Free report right | Free statutory report from each agency | Free weekly reports via AnnualCreditReport.com |
If you're in the USA, the Consumer Financial Protection Bureau's own guidance is the clearest source on this: checking your own credit is a soft inquiry and doesn't affect your score, while hard inquiries from applications can. If you're in the UK, Experian's guide to searches and the Information Commissioner's Office credit pages say the same thing in local terms.
Do employers and landlords check your credit?
Sometimes — and this is another area where people assume the worst. In the UK, some employers run a credit check for roles involving money, and some landlords or letting agents run one as part of referencing. These are usually soft searches, and in the UK an employer needs your consent to run one. They don't affect your score, and they're not the same as a lender's check: an employer typically sees a summary, not your full file, and they can't see your score the way a lender does.
In the USA, employer credit checks are more common for financial roles, but they're also soft inquiries, and under federal law (the Fair Credit Reporting Act) the employer needs your written permission first. Landlords in the USA do commonly pull your report — again, usually as a soft inquiry for tenant screening, though some screening services use a hard one, so it's worth asking.
The practical point: if an employer or landlord wants to check your credit, ask which kind of check it is. If it's soft — and it almost always is — it costs you nothing. And if you've been checking your own file regularly, there won't be any surprises in it anyway.
A hard search you didn't authorise: what to do
Every so often someone spots a hard search they don't recognise. Don't panic, but don't ignore it either — it could be a mistake, or it could be someone using your details. Here's the order that works:
- Check all three agencies. A search might show at one agency and not the others. Note the company name and date exactly as it appears.
- Contact the company first. Ask what the search relates to. Sometimes it's a legitimate check you'd forgotten — a phone contract upgrade, a finance agreement, a joint account. If they can't explain it, ask them to remove it.
- Raise a dispute with the agency. If the company won't help, dispute the search with the credit reference agency holding the record. In the UK, you can also add a notice of correction explaining your side while it's investigated.
- Escalate if it stalls. In the UK, the Information Commissioner's Office handles complaints about credit files. In the USA, you can dispute with the bureau and file a complaint with the Consumer Financial Protection Bureau.
- Check for fraud. If the search sits alongside accounts you don't recognise, treat it as possible identity fraud: contact the agency's fraud team, and in the UK consider a protective registration with CIFAS.
One search you didn't make won't wreck your score on its own. But an unexplained search is a warning light — it's how people first discover someone else is borrowing in their name. That's the real reason to look at your file regularly, not the score itself.
What to actually look at when you check
Most people open their report, glance at the number, and close it. The number is the least useful part. Here's what actually matters, in the order to check it:
- Accounts you don't recognise — the biggest red flag there is. Anything unfamiliar deserves a phone call.
- Searches — scan the hard ones. Do you recognise every company? Any surprises go through the dispute steps above.
- Payment history — any late or missed markers that are wrong, or that you've already settled.
- Personal details — wrong addresses and old names cause mismatches that can quietly block applications.
- Financial associations — old joint accounts or shared finances with someone you're no longer connected to. You can ask to have these removed ("disassociated") if the financial link is genuinely over.
- Electoral roll entry — being registered at your current address helps lenders verify you. It's a small thing that causes an outsized number of declined applications when it's missing.

If you find an error, fixing it is usually a letter or an online form to the agency, with evidence attached. Agencies generally have around a month to investigate in the UK. And if the error was dragging your score down, correcting it is one of the few things that can genuinely lift your score quickly — which is another reason checking beats worrying. Our guide to improving your credit score covers the fixes that actually move the needle, and our comparison of Experian, ClearScore and Credit Karma helps you pick where to check.
How often should you check?
As often as you like — genuinely. There is no limit, no penalty, and no downside to checking daily if that's your thing. For most people, though, a simple routine covers it:
- Once a month — a quick look at one agency, rotating through the three over the year so you see all of them.
- Three months before any big application — a mortgage, a large loan, car finance. That gives you time to fix errors, pay down card balances, and let recent searches age.
- Straight away — if an application is refused, your score drops suddenly, or you get a letter about an account you don't recognise.
Set a monthly reminder and it becomes a five-minute habit, not a chore. Checking monthly also means you notice problems while they're small — a wrong address, a search you didn't make — instead of discovering them the week you need a mortgage.

Before a mortgage: your search timeline
Mortgages are where searches matter most, because the amounts are huge and lenders look hardest. Here's a timeline that keeps your file clean:
- 6 months out: Check all three reports. Fix errors, close nothing in a panic, and stop applying for new credit you don't need.
- 3 months out: Run eligibility checkers and soft-search decisions in principle. Compare lenders without leaving a single hard mark.
- 1 month out: Pick your lender (or let a broker pick for you) and make the one full application. One hard search, on the application most likely to succeed.
- After approval: Don't apply for anything else until the mortgage completes. A fresh hard search between offer and completion can make a lender re-check — and nobody wants that conversation.
If you're working on the bigger picture — paying down what you owe before you apply — our guide to paying off debt fast pairs well with this one. Less debt means less risk in a lender's eyes, and it usually matters far more than any search ever will.
Frequently asked questions
Does checking my credit score lower it?
No. Checking your own score or report is recorded as a soft search, which has no effect on your score and isn't visible to lenders. You can check as often as you like.
Will checking my credit report affect my mortgage application?
No — it helps it. Lenders run their own searches when you apply, and your own checks don't change what they see. Checking early lets you fix errors and avoid applying to lenders who would decline you.
How often can I check my credit report?
As often as you like, at no cost to your score. A sensible routine is once a month, plus a full check of all three agencies a few months before a mortgage or large loan application.
What is the difference between a soft search and a hard search?
A soft search is a look at your file that isn't a credit application — your own checks, eligibility checkers, quotes. A hard search happens when you formally apply for credit, and other lenders can see it. Soft searches never affect your score; hard searches can, slightly and temporarily.
How long does a hard search stay on my credit file?
In the UK, hard searches are visible to lenders for around 12 months, and their effect fades well before that. In the USA, a hard inquiry stays on your report for 2 years, but its effect on your score mostly fades after about 12 months.
Do employers see my credit score when they check?
Not the way a lender does. Employer checks are usually soft searches, need your consent, and typically show a summary rather than your full file and score. They don't affect your score.
Does checking with all three agencies hurt my score?
No. Checking your own file at Experian, Equifax and TransUnion creates three soft searches, and none of them affect your score or show to lenders. Checking all three is actually the smart move before a big application, because each agency can hold different information.
Can a hard search be removed?
Only if it's wrong. If a search was made without your permission or in error, dispute it with the company that made it and then with the agency. A legitimate search from a real application can't be removed early — but it fades on its own within about a year.
Your next step
Stop worrying about looking, and start looking. Check your file this week — free, at any agency — and actually read the searches section while you're there. If everything looks familiar, you're done, and you can stop thinking about it until next month. If something doesn't look right, you've just caught it early, which is the whole point. Your score isn't something you protect by ignoring it. It's something you protect by knowing what's in it.
Sources: Experian's guide to searches and credit checks, the Information Commissioner's Office credit pages, and the US Consumer Financial Protection Bureau's guidance on credit inquiries. Figures on how many UK adults check their files come from the FCA's Financial Lives survey 2024.
Experian: What is a credit check? Hard & soft searches · ICO: Credit · CFPB: What is a credit inquiry?